Protecting Your Business Without Losing Sight of Your Priorities

Business protection should support the organisation’s priorities rather than compete with them. Owners need to invest in people, equipment, marketing, technology and working capital, while also managing risks that could disrupt those plans. The challenge is to make protection decisions in a disciplined way without treating every possible risk as equally urgent.

A useful starting point is to identify what the business most needs to keep operating. That might include a premises, specialist machinery, reliable digital systems, key staff or access to important suppliers. These priorities differ between organisations, so an insurance discussion should begin with the actual operation rather than a standard shopping list.

Management can then consider what could threaten those priorities. Some risks may be reduced through better procedures, maintenance, staff training or security. Others may be accepted because their potential impact is small. Insurance may be appropriate where the business wants to transfer certain financial consequences, subject to the terms of the policy.

A business insurance adviser can help organise this discussion by asking for information about the company’s activities, assets, people and contracts. The value of that conversation depends on the quality of the information provided. A business that understates changes or relies on old figures may find it harder to assess whether its arrangements still fit.

Budget remains an important constraint. The aim is not to buy every available form of cover, but to direct resources towards risks that matter to the organisation. Comparing options should involve more than premium. Limits, excesses, exclusions, definitions and conditions can influence the value of a policy in a particular situation.

It is also helpful to look at the costs that insurance cannot solve. An interruption may damage customer relationships, consume management time or delay strategic projects even where some financial loss is insured. This is why continuity planning sits alongside insurance. Backup suppliers, documented procedures, data recovery and delegated authority can help the business respond more effectively.

Contracts deserve separate attention. A landlord, customer or supplier may require certain insurance arrangements, but contractual language can also create obligations outside the scope of a policy. Legal advice may be appropriate when interpreting those duties. A business insurance adviser can address insurance-related questions, but should not be treated as a substitute for legal advice.

Protection priorities should change when the business changes. A new location, product, service, major client or technology platform can alter the balance of risk. Management can create simple triggers that prompt a review instead of waiting automatically for renewal.

The process should also include a record of decisions. A short note explaining which risks were considered, what information was used and why an option was selected can be valuable later. It creates continuity if staff change and makes the next review more efficient.

Periodic scenario testing keeps the discussion practical. Ask what would happen if a key site closed for a week, a major system failed, stock was damaged or an important supplier stopped delivering. The exercise can reveal whether the business has realistic alternatives and sufficient financial resilience.

Working with a business insurance adviser can help keep these questions connected, but the final protection strategy should reflect management’s priorities, resources and tolerance for risk. When insurance is considered alongside operational controls, contracts and continuity planning, the business can protect what matters without losing sight of the investments and decisions that support growth.

Some losses create an immediate need for cash, while others develop over weeks. Thinking about timing helps management decide which contingency arrangements must be available straight away.

The company should also consider how much uncertainty it is willing to accept. Retaining a manageable risk may be reasonable, while a risk that could threaten operations may call for a different response. These judgements should be revisited as finances and strategy change.

Finally, the review should be understandable to more than one person. A brief written summary can preserve the reasoning, highlight unresolved questions and make future updates faster.
The Risks That Can Hide in Your Daily Business Operations

Daily routines can make risk feel ordinary. A delivery arrives, a payment is processed, a contractor enters the premises and staff exchange customer information. Nothing unusual may happen for months, which can create confidence that the process is safe. Yet repeated tasks often contain small exposures that become visible only when there is an error, delay or dispute.

Consider a business that receives stock several times a week. The obvious concern may be damage to goods, but the wider process includes vehicle movements, manual handling, storage, access to loading areas and the possibility of sending incorrect items to customers. A change in supplier, packaging or delivery volume can alter that risk without anyone formally changing the procedure. Reviewing the whole sequence can reveal where controls have weakened.

The same principle applies to routine work performed away from the main premises. Employees may visit customer sites, carry tools, drive between appointments or use temporary work areas. The organisation should know who is responsible for equipment, how incidents are reported and whether the work differs from the activity originally described when insurance was arranged. A business insurance adviser can help frame questions around these operational changes, while managers provide the detailed facts about how work is actually performed.

Administrative tasks can carry less visible exposures. A member of staff might send confidential information to the wrong recipient, approve a fraudulent invoice or rely on outdated customer instructions. These events can involve financial loss, privacy concerns or professional disputes depending on the circumstances. Clear approval steps, access restrictions and staff training are practical controls. Insurance may form part of the response, but it should not be treated as a substitute for careful processes.

Supplier dependence is another everyday issue that can stay hidden. A business may believe it has several suppliers while relying on one provider for a critical component, delivery route or digital service. If that provider fails, alternative sources may take time to arrange. Mapping these dependencies helps management understand what could interrupt trading and how quickly the business could recover.

Small changes can also accumulate. A company may add new services, employ casual staff, store more stock or begin taking work in another region without considering whether its risk profile has shifted. None of these steps necessarily creates a problem by itself. Together, however, they can make older assumptions less accurate. Periodic conversations with a business insurance adviser can be useful when the purpose is to compare current activities with the information on which existing cover was based.

Contracts deserve similar attention. Standard customer agreements, leases and supplier terms may contain responsibilities that employees accept without escalating them. Some clauses may affect liability or require particular evidence of insurance. Because contract interpretation is a legal matter, businesses should obtain legal advice where needed rather than assuming an insurance policy resolves the issue.

The best way to uncover hidden operational risk is to follow real work from start to finish. Ask what could fail, who would notice, what the immediate cost might be and what would happen next. Include near misses as well as actual losses, because they often show where a process is fragile.

That review should lead to practical action, such as changing a procedure, improving records or clarifying responsibility. It can also provide better information for a business insurance adviser when discussing whether current arrangements still reflect the organisation. Routine operations may look familiar, but familiarity is not the same as low risk.

The review should also include how complaints and incidents are escalated. Front-line staff need a simple way to report something unusual before it develops into a larger problem. Patterns in small incidents can reveal weak procedures, recurring customer issues or equipment concerns that deserve attention.

The Cost of Overlooking Everyday Business Risks

Everyday business risks rarely arrive with a warning label. A damaged laptop, a customer trip, a missed delivery, a minor leak or a short system outage may look manageable at first. The real cost can grow when the event interrupts work, affects customers or creates extra expenses that were not planned.

Routine risks deserve practical attention because they arise within normal operations.

Look Beyond the Immediate Repair

When something breaks, owners naturally focus on the direct cost. A damaged piece of equipment may need repair or replacement, but that may be only the first expense. Staff can lose productive time, orders can be delayed and customers may need updates or alternative arrangements.

A business insurance adviser can help an owner discuss which losses may fall within current cover. Policy wording, limits, excesses, exclusions and circumstances still matter, so insurance should not be treated as guaranteed reimbursement.

Minor Incidents Can Reveal Process Weaknesses

A small problem can expose a larger weakness in how the business operates. If one computer failure stops invoicing, the issue may be a lack of backup systems. If one absent employee leaves nobody able to complete an essential task, the issue may be poor knowledge sharing.

Recording near misses and small disruptions can show where the business relies too heavily on one person, device, supplier or process.

Customer Impact Can Outlast the Event

A short interruption may have a longer effect if customers receive late work, unclear communication or inconsistent service. The financial impact is not always easy to measure, but relationships can be affected when expectations are not managed.

Clear incident communication is part of risk control. Staff should know who contacts customers, what can be shared and how alternatives are arranged.

Documentation Matters Before a Claim

Owners sometimes think about evidence only after a loss. Keeping organised records beforehand can make it easier to understand what happened and provide information if a claim is made. Useful records may include asset lists, purchase information, maintenance notes, photographs, contracts and incident reports, depending on the situation.

A business insurance adviser may also suggest reviewing policy documentation so the owner knows where to find key contacts and what notification steps may apply. The actual policy should be checked because requirements can differ.

Prevention Often Starts With Routine Maintenance

Many business controls are simple rather than dramatic. Regular equipment checks, safe storage, housekeeping, staff training, software updates and secure backups can lower the chance that a small weakness turns into an interruption.

Assigned responsibilities and recorded checks make the business less dependent on memory.

Review Costs That Continue During Disruption

Even a brief interruption can leave fixed commitments in place. Rent, finance payments, subscriptions, wages and supplier obligations may continue while revenue is reduced. Owners can improve planning by listing which costs would remain during different scenarios.

That exercise does not replace insurance advice, but it helps define the financial pressure a disruption could create. It can also support a more focused discussion about continuity arrangements and possible cover.

Use Everyday Events to Improve the Risk Plan

Risk management works best when it reflects real experience. Repeated delivery delays, technology problems or customer incidents can reveal dependencies and weak processes.

Rather than dismissing each event after it is resolved, owners can look for patterns and decide whether controls need to change.

A business insurance adviser can contribute to the insurance side of that review, while management focuses on prevention, continuity and clear procedures. The cost of overlooking everyday risks is not always a single large bill. It can be repeated lost time, avoidable disruption and growing uncertainty. Paying attention to small signals helps a business make calmer decisions before the next problem becomes harder to manage.

The review can be kept proportionate. A small business may use a short monthly checklist, while a larger organisation may assign formal responsibilities across teams. What matters is that recurring issues are noticed, recorded and followed through rather than treated as isolated inconveniences.

Discover a Different Side of Sydney From Bella Vista

Harbour landmarks may dominate the usual image of Sydney, but the city stretches far beyond the CBD. Bella Vista and Norwest sit in the Hills District, an area shaped by local neighbourhoods, business precincts, parks and community destinations. For travellers visiting the north-west, choosing Visy Dior hotel Sydney can make it easier to experience this side of the city without building every day around a return trip to the harbour.

Start locally

Visy Dior is located at 1 Columbia Court in Norwest, close to Bella Vista. Bella Vista Farm is a short drive away and offers a local heritage setting that feels very different from central Sydney’s high-rise streets. The surrounding area also includes cafes, restaurants and everyday services used by residents and workers. Spending some time nearby can give a visitor a more grounded sense of the Hills District rather than treating it only as a place to sleep.

Keep the wider city within reach

A north-western stay does not mean ignoring the rest of Sydney. Current accommodation listings place Norwest Metro Station within walking distance of the property, giving guests a public-transport option for reaching other parts of the city. Driving may suit some trips better, particularly when the day includes several suburban stops. The useful approach is to match transport to each outing and check live journey information before setting off.

Make the hotel part of slower days

Visy Dior hotel Sydney currently promotes 132 rooms, an outdoor pool, fitness facilities, event spaces and on-site dining. That means a day does not have to be packed with sightseeing to feel worthwhile. Guests might spend a quieter morning at the property, meet local friends for lunch, or use the hotel as a comfortable reset point between plans. Specific facilities and opening arrangements should be confirmed before travel because hotel operations can change.

Use Bella Vista as a different starting point

From this part of Sydney, the itinerary can be organised around the Hills District first and the CBD second. That can suit wedding guests, families visiting relatives, business travellers and repeat visitors who have already seen the best-known central attractions. Visy Dior can also be practical for events held at the property itself, allowing guests to move from a function to their room without an additional cross-city journey.

Choose the base that fits your version of Sydney

There is no single correct neighbourhood for a Sydney stay. A first-time visitor focused entirely on the Opera House, harbour and inner-city museums may prefer to stay centrally. Someone whose plans are in Norwest, Bella Vista or nearby suburbs may gain more from Visy Dior hotel Sydney because the location follows the trip they are actually taking. The Hills District offers a different perspective on the city: less about racing between icons, and more about local connections, business, events and neighbourhood life. A thoughtful base can make that different side of Sydney feel intentional rather than out of the way.

Plan one contrast day

One way to make the location work is to plan a deliberate contrast. Spend one day around Norwest and Bella Vista, then choose another for the harbour, inner city or a museum visit. That avoids treating every day as a long return commute and makes the difference between neighbourhoods part of the experience. Travellers can also use local dining or hotel facilities on the quieter day rather than trying to squeeze another landmark into the schedule.

For guests with events or meetings nearby, this approach keeps the practical reason for the trip at the centre while still allowing time for classic Sydney sights. It is a simple way to see more than one version of the city without making the stay feel like a transport challenge. The result is not a lesser Sydney experience, just one organised from a different starting point. Checking transport updates before arrival can make that day easier to organise. It leaves room to change plans if weather, traffic or a late-running commitment affects the itinerary.

Using Your Own Tissue to Restore What Time Has Changed

Ageing does not affect only the skin. Facial fat compartments can change, bone structure gradually remodels and skin elasticity alters, which can make some areas look flatter or less supported. Similar volume changes can also follow weight change, illness or previous surgery. Because several tissues are involved, restoring volume is not as simple as filling every hollow. The first step is understanding what has actually changed and whether a procedure is appropriate for that pattern.

What using your own tissue means

In fat transfer, a surgeon removes fat from one area of the body, processes it and places selected fat into another area where additional volume is wanted. The technique uses the person’s own tissue, but it is still a surgical procedure. It requires a suitable donor area, careful planning and an understanding that not every transferred fat cell will necessarily remain long term. The amount that persists can vary, so results are not perfectly predictable.

Why planning matters

A surgeon considers both the donor and recipient areas. Taking too much from one place or placing too much in another can create contour problems, so the plan needs to account for proportions rather than focusing on a single measurement. Previous surgery, medical conditions, smoking, medicines and healing history can also affect suitability. A consultation should include realistic alternatives, including doing nothing, and should explain what may happen if the desired result is not achieved in one stage.

Recovery is part of the procedure

Swelling, bruising and tenderness can occur in both the area where fat is taken and the area where it is placed. Recovery experiences vary depending on the extent and location of surgery. People need clear instructions about wound care, activity, garments if used, and when to seek medical review. It is sensible to plan around recovery rather than assume the treatment will fit easily between major commitments. Any surgery can involve complications, and individual risk should be discussed with the treating surgeon.

Natural tissue does not mean risk-free

The appeal of fat transfer is often linked to the use of the person’s own tissue and the possibility of restoring volume without relying solely on an implanted or injectable filler material. However, “natural” should not be confused with harmless. Infection, bleeding, contour irregularity, asymmetry and other complications are possible, and some procedure sites carry particular risks. Patients should ask about the surgeon’s training, the facility, anaesthesia, follow-up and how complications are managed.

A long-term view

Volume restoration works best when it is planned around the individual rather than a fixed ideal of youth. The aim may be to restore proportion, soften a hollow or rebuild volume after another change, but no procedure stops ageing. For the right patient, fat transfer can be one option within a broader surgical plan. The decision deserves time, informed consent and a clear discussion of uncertainty as well as potential benefit. Anyone considering surgery should seek assessment from an appropriately qualified medical practitioner and avoid relying on promotional images as a substitute for personalised advice.

What to ask before deciding

A useful surgical consultation should make the practical pathway clear. Patients can ask where the operation will take place, what type of anaesthesia may be used, who provides after-hours support and how follow-up is organised. They can also ask how the surgeon approaches asymmetry, what happens if some of the transferred volume is lost and whether another procedure might be needed. Before-and-after photographs may help illustrate a surgeon’s work, but they cannot promise the same outcome for someone else. 

Costs, time away from work and help at home can also affect whether the timing is right. Taking these details seriously is part of the treatment decision, not an administrative extra. A procedure that uses the patient’s own tissue still requires the same careful thinking expected of other surgery, including realistic planning for recovery and a willingness to postpone if health or circumstances make that the safer choice.

Designing Site Boundaries Around Real World Threats

A useful site boundary is designed around events that could plausibly occur, not around a vague idea of danger. A retail loading yard, utility compound, warehouse and office campus hold different assets and attract different types of unwanted access. The starting point is therefore to identify what needs protection, who might try to reach it and what the consequences would be if the perimeter were crossed.

That exercise should include ordinary problems as well as deliberate intrusion. Trespass, theft, vandalism, accidental public access and vehicle entry may all be relevant. The perimeter barrier can then be specified to address those scenarios rather than chosen mainly for appearance or because the same product has been used elsewhere.

Map the perimeter as a series of approaches

Threats rarely arrive evenly from every direction. One boundary may face a well-used street with good lighting, while another backs onto vacant land, a laneway or neighbouring storage area. People approaching from those locations have different levels of visibility and different opportunities to test the perimeter without being noticed.

Walking the site can reveal issues that plans miss. Ground levels, vegetation, street furniture, adjoining walls and parked vehicles may create easier climbing points. Informal tracks can show where people already move. Looking from outside towards the property is particularly useful because it reflects the perspective of someone approaching the boundary rather than someone who already understands the site.

Match the barrier to the consequence

Not every edge needs the most resistant available treatment. Higher protection may be justified around valuable plant, hazardous materials or sensitive operations, while lower-risk areas may need a simpler boundary. A proportionate approach concentrates cost and attention where a breach would matter most.

Well-chosen security fencing also needs to fit its environment. Exposure to salt, dust, impact or vegetation can affect durability. Visibility may be more valuable than privacy in some areas, while screening may be important in others. The boundary should support surveillance and site use instead of creating blind spots or maintenance problems that weaken performance later.

Design gates around pressure points

Access points experience more stress than continuous fence lines because they combine security with movement. Deliveries may arrive in clusters, staff may enter during shift changes and visitors may need help before they are admitted.

Separating pedestrian and vehicle movement can reduce conflict where space allows. Queuing areas should also be considered so waiting vehicles do not block roads or force gates to remain open. The design needs to account for emergency access and authorised after-hours entry without making routine operation unnecessarily complicated.

Plan for people, maintenance and change

Even a strong perimeter depends on the people who operate it. Staff need clear procedures for faults, lost credentials, visitors and gates that fail to close. Contractors should know which areas are restricted and who can approve temporary openings. These processes help the physical design work as intended during busy periods.

Maintenance access must be practical too. Vegetation needs trimming, hardware needs adjustment and damaged sections need repair. If access for these tasks is difficult, small defects can remain for longer. Inspection routes should make it easy to see both sides of important boundary sections where possible.

Finally, real threats and site layouts change. New neighbouring development can increase foot traffic, a business may begin storing different goods, or an extension may move valuable assets closer to the perimeter. The security fencing that was appropriate when installed may need to evolve. Reviewing security fencing after operational changes keeps the design connected to current risk.

Designing around real-world threats does not mean predicting every possible incident. It means building from credible scenarios, understanding how the site can be approached and making sure barriers, gates, surveillance and procedures support one another. That creates a boundary that is practical enough to operate every day and strong enough to matter when it is tested.

Keeping Stock at the Right Temperature Without Wasting Energy

Energy use and temperature control can look like competing priorities. One seems to push a business towards less cooling, while the other demands reliable cold conditions at all times. In practice, the better target is not simply “use less refrigeration”. It is to remove wasted load while keeping stock within the conditions it requires.

Start with the temperature requirement

Different products have different storage needs, so set-points should be based on the applicable requirements for the stock and the equipment. Setting a system colder than necessary can increase workload without adding useful protection, but setting it too warm creates a different risk. Food businesses should follow relevant food-safety guidance and their own procedures.

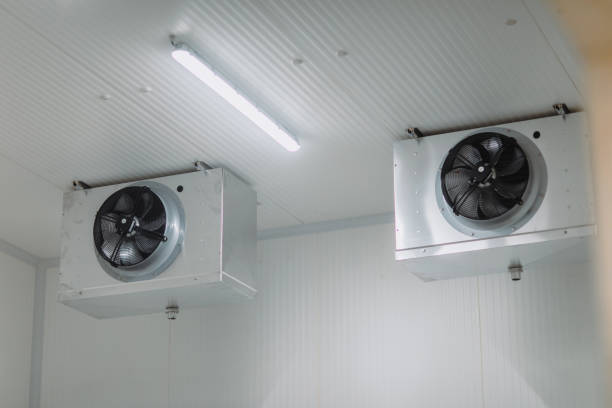
Commercial refrigeration solutions should also be checked for temperature consistency, not only the number shown on one display. Poor airflow, overloaded shelves or frequent door opening can create local warm areas even when the controller appears normal.

Reduce the heat entering the space

Every open door admits warmer air. In a busy kitchen or shop, dozens of unnecessary openings can add up. Organising stock so commonly used items are easy to find helps staff work faster without asking them to sacrifice service.

Deliveries matter as well. Loading large amounts of warm product creates a significant cooling demand. Where appropriate, businesses can plan receiving and storage so the refrigeration system is not repeatedly hit with avoidable peaks.

Keep seals and airflow working

A worn door gasket can leak continuously, while blocked vents can prevent cold air reaching parts of a cabinet or room. Both problems force the system to work harder for poorer results. Visual checks are simple, but damaged components should be repaired properly rather than improvised.

Cleanliness outside the cold space matters too. Condensers need to reject heat. Dust, grease or restricted ventilation can make that harder. Maintenance requirements vary, so cleaning and servicing should follow equipment instructions and be completed safely.

Use controls intelligently

Modern commercial refrigeration solutions may include electronic controls, alarms or monitoring that help reveal temperature patterns and run behaviour. Data can show whether a room warms at the same time each day, whether a door is being left open or whether equipment is taking longer to recover after loading.

The point is not to collect graphs for their own sake. A useful monitoring system should support decisions, alerts and maintenance. Settings should also be protected from casual adjustment so a well-meaning change does not create instability.

Staff habits can support the technical measures. Training does not need to turn every employee into a refrigeration specialist. It can simply explain why doors should close promptly, why vents must stay clear and why unusual frost or temperature changes should be reported. Commercial refrigeration solutions perform inside a real workplace, so everyday behaviour becomes part of their operating environment whether the business plans for it or not.

Maintain before efficiency slips

commercial refrigeration solutions can decline in performance gradually. Fans, seals, sensors and other components wear, while coils can become dirty. Preventive maintenance gives a business a chance to correct those issues before they show up as higher energy use or unreliable temperatures.

Taurus Refrigeration Services is a New South Wales business associated with commercial refrigeration and air-conditioning work. Whichever provider a site uses, service discussions are more productive when staff can share temperature records, operating patterns and recurring symptoms.

Match capacity to real operations

Equipment that is poorly matched to demand may cycle excessively, struggle during peak periods or operate inefficiently. When replacing or expanding a system, businesses should describe actual door use, stock loads, ambient conditions and service patterns rather than relying on floor area alone.

Keeping stock at the right temperature without wasting energy is a systems problem, not a single setting. Good commercial refrigeration solutions combine appropriate design, disciplined use, maintenance and useful monitoring. When those elements work together, the business can protect its stock while reducing the unnecessary heat, leakage and poor operation that make refrigeration work harder than it needs to.

What Does Negative Balance Protection Actually Cover?

Negative balance protection addresses a specific problem created when leveraged losses move faster than an account can absorb them. If qualifying losses push an account below zero, the protection can limit the customer’s liability so that the deficit is not ultimately owed. Its precise scope, however, depends on the legal and contractual rules applying to the account.

A cfd broker offering this protection is not promising that positions cannot suffer severe losses or that deposited capital will remain intact. The distinction is between losing money held in the account and becoming liable for an additional deficit after that money has been exhausted.

Protection Usually Addresses the Deficit, Not the Trading Loss

An account containing $8,000 can still lose most or all of that amount despite negative balance protection. The mechanism becomes relevant when recognized losses would otherwise take the qualifying account below zero.

If positions are closed with the account showing negative $1,400, protection may require the covered deficit to be adjusted so the customer does not remain liable for that $1,400. It does not normally restore the original $8,000.

The zero boundary is therefore central to understanding the feature. Protection against a negative balance should not be confused with protection against losing the positive balance already committed to trading.

Fast Gaps Show Why the Protection Exists

Ordinary margin controls are designed to close positions before account resources are exhausted, but execution cannot always occur at the level where a close-out process begins. A discontinuous price move can pass through available prices.

Imagine a share index CFD trading at 7,450 before its underlying market closes. An account holds a leveraged long position with enough equity to withstand a moderate decline. Unexpected information arrives while the main venue is shut, and the index reopens near 7,080. There were no executable prices at many of the intermediate levels.

Closing the position around the newly available market could produce a loss exceeding the remaining account equity. Negative balance protection becomes relevant to the resulting deficit, not to the unfavorable reopening price itself.

Stop-Loss Orders and Balance Protection Solve Different Problems

A stop order attempts to control where a position exits once its trigger conditions are met. Negative balance protection concerns what happens to the account if realized losses exceed the funds available.

Combining the two concepts can create a misleading assumption that a protected account also guarantees stop execution. An ordinary stop may still experience slippage during a gap or thin market. The loss can consume substantially more equity than anticipated even if a subsequent balance adjustment prevents an eligible deficit from remaining payable.

One mechanism concerns execution; the other concerns ultimate account liability.

Eligibility Can Depend on the Account and Legal Entity

The presence of negative balance protection should never be inferred solely from a platform feature list. A cfd broker may operate through different legal entities, and protections can vary according to jurisdiction, customer classification, account agreement, or applicable regulatory framework.

Retail and professional classifications, for example, may not always receive identical protections. Special account arrangements or contractual provisions can also affect how the mechanism is applied.

A familiar brand name therefore does not by itself establish the terms governing a particular account. The relevant documents are those belonging to the entity that actually holds the customer’s trading relationship.

A Zero Floor Does Not Remove Position-Level Risk

Knowing that a covered deficit may be limited can make an account appear safer than the underlying positions actually are. Yet the protection normally operates only after losses have already become extreme enough to exhaust available resources.

It does not make leverage smaller, reduce a spread, prevent slippage, preserve margin, or stop positions from being liquidated. In that sense, stronger protection against debt can coexist with a trade that remains capable of losing the entire funded balance.

Before opening a CFD position, locate the provider’s negative balance terms and identify the exact account and legal entity they cover. Check whether eligibility depends on customer classification, whether protection is applied per account or under another arrangement, and how deficits are adjusted after close-out. Then calculate the position’s potential loss independently of that protection. The useful question is not merely whether the balance can fall below zero, but how much capital can disappear before the zero boundary becomes relevant.

Security Features to Look for in an Online Trading Platform

Trading account security extends beyond keeping a password private. An online account can contain personal information, payment details, open positions, stored preferences, and access to functions capable of changing financial exposure. A platform’s security design should therefore limit unauthorized entry while also making unusual account activity visible quickly.

When comparing forex trading platforms, security features deserve examination as an interconnected system rather than a collection of reassuring labels. Strong login protection is valuable, but its benefit is reduced if account recovery, device management, or transaction monitoring creates an easier route around it.

Multi-Factor Authentication Should Protect More Than Login

Multi-factor authentication adds another verification requirement after a password, making stolen credentials less useful on their own. The implementation matters as much as the presence of the feature.

Protection is stronger when sensitive account changes also require additional verification. Changing a password, adding a withdrawal method, modifying contact information, or registering a new device can carry greater consequences than simply viewing the account.

A useful review should establish which actions trigger verification and what happens if access to the second factor is lost. Recovery procedures that rely on weak identity checks can undermine otherwise strong authentication.

Device and Session Controls Should Expose Unexpected Access

Account owners should be able to identify where active sessions exist and terminate ones they do not recognize. Useful information may include device type, approximate login location, access time, or other session details provided by the service.

Imagine an account normally accessed from one desktop and one phone. A new browser session appears while the account holds an open GBP/CHF position. The market itself has not changed, but an unauthorized session could alter the stop, increase exposure, or close the position.

A platform that records the session and sends a new-login notification gives the account holder an opportunity to react before the security problem becomes a trading problem.

Encryption Should Cover Data in Transit

Financial credentials and account instructions pass between the user’s device and remote systems. Secure transmission helps prevent information from being exposed while moving across that connection.

Encryption, however, does not prove that the website receiving the information is legitimate. A fraudulent login page can also use an encrypted connection. The padlock symbol in a browser may confirm that traffic to a site is protected while saying nothing about whether the site belongs to the intended provider.

Security checks should consequently include the domain, application source, and provider identity rather than relying on one browser indicator.

Account Alerts Should Focus on Changes That Alter Control

Notifications can provide an early warning when an account behaves differently from its normal pattern. Useful alerts include password resets, new-device access, contact-detail changes, withdrawal requests, and other sensitive actions.

For forex trading platforms, notifications tied only to executed orders may leave significant gaps. An attacker who changes recovery information before attempting a transaction has already altered control of the account even though no position has moved.

More notifications are not necessarily safer. Excessive low-value messages can bury the event that actually requires attention. Alerts are most effective when important account changes are clearly distinguishable from ordinary platform activity.

Recovery Procedures Need Security Equal to the Main Login

Password recovery is designed for moments when normal authentication cannot be completed, which makes it an especially important part of the security architecture. If the recovery route is substantially weaker than the normal login process, it can become the preferred point of attack.

Users should examine how identity is verified, where reset messages are sent, how compromised contact details can be corrected, and whether suspicious recovery attempts generate warnings. Backup codes or other recovery credentials also need secure storage away from the device routinely used to access the account.

Before funding or actively using an online trading account, test its security controls without placing a live order. Enable the strongest available authentication method, inspect active sessions, confirm alerts for new devices and account changes, review the recovery procedure, and verify the official login domain and application source. A platform should make unauthorized access difficult, but it should also make an attempted takeover difficult to hide.

Charting Features Useful for Currency Market Analysis

Charting software can display enormous amounts of currency data, but useful analysis depends on how that information is arranged. The strongest features are not necessarily those that add more signals. They are the ones that help reveal changes in direction, pace, participation, and the relationship between current price and earlier trading.

Modern forex trading platforms usually provide far more chart controls than a trader needs at once. Selecting a small set with distinct analytical jobs can make the screen easier to interpret while reducing the temptation to treat several versions of the same evidence as independent confirmation.

Flexible Time Compression Reveals How a Move Developed

Changing chart intervals does more than enlarge or shrink candles. It changes which parts of price behavior become visible. A daily chart may show that a currency pair remains inside a broad advance, while an hourly view reveals repeated failures to extend that move.

Time compression is particularly useful when the intended holding period sits between very short and very long horizons. Instead of demanding identical signals from several intervals, each view can answer a separate question: where the larger move stands, how the current leg developed, and whether recent behavior is becoming less orderly.

Session Markers Expose Where Price Activity Was Concentrated

A 24-hour currency chart can hide the fact that price behavior changes as regional participation rotates. Session separators, time labels, and period markers help connect a move with the part of the trading day in which it occurred.

Repeated highs formed during one active window may carry different information from scattered highs created during thin trading. Marking session boundaries can also show whether a breakout gained follow-through when a new financial center became active or faded as participation increased.

The chart becomes a record of when movement occurred, not merely where.

Volatility Measures Show When the Market Changes Its Pace

Range-based indicators can identify whether recent candles are expanding or contracting without predicting direction. Their value lies in comparing current movement with the pair’s own recent behavior.

Imagine GBP/NZD spending several sessions with an average hourly range near 18 pips. The range then expands toward 35 pips as UK and New Zealand rate expectations begin moving in opposite directions. A breakout appears on the chart, but the larger ranges also mean that a stop distance calibrated to the earlier environment can now be reached by ordinary intraday movement.

A volatility feature therefore changes how a price level is interpreted even when the level itself has not moved.

Price Overlays Make Relative Performance Visible

Some forex trading platforms allow another instrument or data series to be compared with the primary chart. Used carefully, overlays can test whether a currency move is isolated or appears alongside a related market.

A commodity-sensitive currency, for example, may be compared with a relevant raw-material market, while a currency pair can be viewed alongside a yield measure when rate differences are central to the analysis. Divergence does not prove that one market is wrong. It can reveal that the assumed relationship has weakened or that another influence has become more important.

Adding a related market can actually simplify analysis when it replaces several indicators derived from the same currency price.

Drawing Layers Preserve the Evolution of a Market Thesis

Annotations, rectangles, channels, and labeled levels can document how an analysis changes over time. Their strongest use is not filling the chart with permanent lines, but distinguishing active observations from levels that have already lost relevance.

A prior consolidation can be shaded, a failed breakout labeled, and an invalidation area marked separately from a possible entry. As price develops, obsolete objects can be removed rather than allowed to accumulate. The remaining chart then shows which assumptions are still being tested.

Before acting on a currency setup, configure the chart so each visible feature has one defined task. Use one view for time structure, mark the relevant session, compare current range with recent movement, add a related market only when there is a clear economic link, and retain only drawing objects tied to the present thesis. If two features answer the same question, remove one before deciding on the trade.